Why Does Prevention Cost Less Than Rework in Bag Manufacturing?
- Why Quality Cost Is Measured in the Wrong Place
- The Four Cost Categories
- What Prevention Buys
- What Failure Costs
- The Asymmetry of Cost by Stage
- Measuring Your Own Numbers
- Why Rework Is Rarely as Cheap as It Looks
- Where Prevention Pays Most in Bag Production
- Where Prevention Stops Paying
- Making the Case Internally
- Who Should Carry the Cost
- Tracking It Over Time
- FAQ
Quality spending is usually discussed as a single budget line, and that is the first reason it is managed poorly. Money spent on a go-gauge at the cutting bench, money spent sorting finished bags and money lost to a market return are three different investments with three different returns.
They also behave differently over time. Prevention is paid once and keeps returning while the order runs. Failure is paid every time the same defect appears, in increasing amounts as the goods move further from the point where the defect was made.
This guide sets out the cost structure behind that asymmetry: why quality cost is often measured in the wrong place, the four categories that make it visible, what prevention actually buys, what failure actually costs, how cost escalates stage by stage, how to measure your own numbers, why rework is rarely as cheap as it looks, where prevention pays most in bag production, where prevention stops paying, how to make the case internally, who should
carry the cost, and how to track it across seasons.
Why Quality Cost Is Measured in the Wrong Place
Most factories and most brands see the cost of quality only where it is invoiced, which is rarely where it is created.
The Visible Line and the Hidden Line
Rework labour, sorting hours, replacements and freight appear on a ledger and are treated as the cost of quality. The larger part — the engineering time spent chasing a defect, expedited material, delayed shipment, lost capacity and the margin given away to keep a customer — usually appears somewhere else or nowhere.
That is why a quality improvement case often looks weak: the investment is visible and the saving is not.
Why Failure Feels Cheaper at the Point of Decision
Choosing between spending on prevention and accepting a defect rate looks like a comparison between a certain cost and an uncertain one. The prevention cost is quoted now; the failure cost is described as a risk.
The asymmetry disappears as soon as failure cost is expressed per unit and multiplied by the order quantity, which is usually a small calculation that changes the decision.
The Accounting Problem
Prevention is often booked as overhead while rework is booked as direct labour, so an order that consumes extra sorting hours looks productive. The same order, costed properly, explains where its margin went.
Where quality cost is tracked per order rather than per department, the comparison becomes visible to the people who decide.
| Cost type | Where it usually appears | Where it is created |
|---|---|---|
| Rework labour | Direct labour | The operation that caused the defect |
| Sorting hours | Direct labour | Inspection stage, caused earlier |
| Replacement goods | Material | The operation that caused the defect |
| Expedited material | Freight | Planning, caused by rework delay |
| Lost capacity | Not recorded | Rework consuming line time |
| Engineering time | Overhead | Root cause work |
| Returns and credits | Sales deduction | Design, material or process |
| Market reputation | Not recorded | Recurring failures |
Why the Categories Are Kept Separate
Grouping all quality spending into one line hides the comparison that matters, because prevention and failure behave in opposite ways as volume grows.
Kept separate, they show whether a season's spend bought fewer defects or merely absorbed more of them.
The Four Cost Categories
Grouping quality spending into four categories makes the structure visible and makes comparison between periods possible.
Prevention
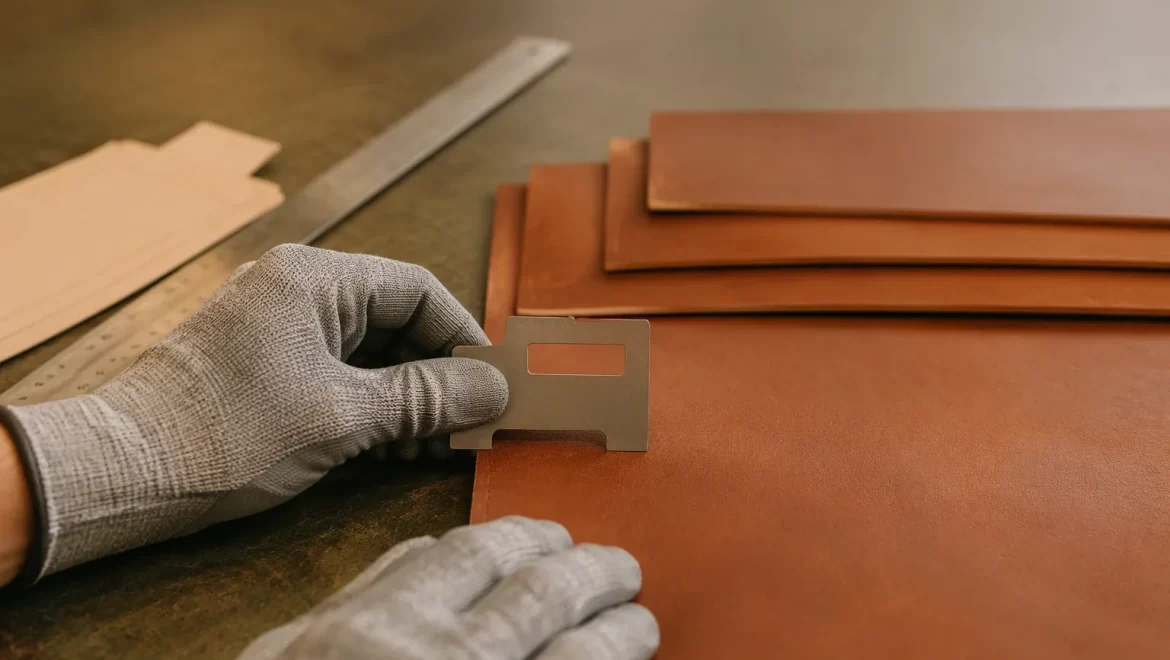
Prevention is spending that stops defects being created: clear specifications, tolerances, gauges and templates, sample approval, supplier qualification, tooling maintenance and training against a written standard.
Appraisal
Appraisal is spending that finds defects: incoming inspection, in-line checks, final inspection and testing. Appraisal does not reduce the number of defects created; it reduces the number that reach the customer.
Internal Failure
Internal failure is what a defect costs when it is found before shipment: rework, sorting, scrap, replacement material and the production time consumed by all of it.
External Failure
External failure is what a defect costs after shipment: returns, credits, freight in both directions, replacement orders, inspection at destination and the commercial consequences of a dissatisfied customer.
| Category | Purpose | Cost behaviour over time |
|---|---|---|
| Prevention | Stop defects being made | Paid once, returns while running |
| Appraisal | Find defects before shipping | Scales with volume |
| Internal failure | Absorb defects found late | Repeats with the defect |
| External failure | Absorb defects found after shipping | Repeats, amplified |
The Cost of a Poorly Written Specification
A specification that leaves a dimension unstated does not save engineering time; it defers the cost to a dispute and to the batch that has to be sorted while the question is settled.
The deferred cost is usually larger than the time that writing the value would have taken, and it arrives at the worst possible point in the schedule.
What Prevention Buys
Prevention spending is often presented as a list of costs with no stated return. Stating what each item buys is what makes the list fundable.
Specifications, Tolerances and Drawings
A written tolerance costs engineering time once and prevents an entire class of arguments. Where a dimension is stated with a limit, the operator can check it, the inspector can verify it and the supplier cannot explain the difference as interpretation.
The return is visible on the first disputed batch: without a stated value, the batch is a negotiation; with one, it is a measurement.
Gauges, Templates and Fixtures
A go-gauge at a cutting bench is cheap relative to the panels it saves. The same logic applies to a stitch-length gauge, a hardware test fixture and a colour viewing box.
These items have a second benefit that is often overlooked: they remove dependence on the judgement of one experienced person, which is what makes output consistent across shifts and across sites.
Sampling, Approval and Qualified Suppliers
Approving a pre-production sample and sealing it defines the reference for everything that follows. Qualifying a supplier before the first order prevents the expensive discovery that the supplier cannot hold a tolerance.
Where a brand sources from several factories, a common standard and sealed samples keep the products comparable, which is a commercial benefit rather than only a technical one.
| Prevention item | What it costs | What it returns |
|---|---|---|
| Written specification | Engineering time | Fewer interpretation disputes |
| Tolerance values | Engineering time | Measurable acceptance |
| Go-gauge or template | Tooling cost | Consistent cutting and forming |
| Hardware test fixture | Tooling cost | Function verified in minutes |
| Sealed sample | Sampling cost | A reference for every batch |
| Supplier qualification | Audit and sample cost | Fewer late discoveries |
| Training against a standard | Time | Consistent workmanship |
| Tool maintenance | Planned downtime | Fewer sudden tool faults |
Recording Prevention Spend Separately
Prevention spend is rarely recorded as a quality item, which is why it appears only as an expense. Booking it separately allows it to be set against the failure cost it removes.
The bookkeeping is minimal: tooling, gauges, qualification and engineering time against a defect class, reviewed once a season.
What Failure Costs
Failure cost is usually estimated from the obvious items and understated by the ones that are hardest to see.
Rework, Sorting and Scrap
Rework consumes line time that has already been paid for, and it delays the operation downstream. Sorting consumes inspection hours and produces the same result as prevention would have, except that the defect has already been made.
Scrap is the clearest cost because material and labour are both lost, and it is the easiest to record.
Replacement, Freight and Schedule
Replacement goods require material that may already be committed elsewhere, and the scheduling consequences usually exceed the material itself: an air shipment to protect a delivery date, a line held waiting for a corrected component.
Where the replacement comes from a second production run, the run consumes capacity that was planned for another order.
Returns, Credits and Market Consequences
A market return carries freight in both directions, inspection and replacement, and it arrives with a customer who has already formed a judgement. Where the same failure repeats, the consequence moves from a credit note to a lost account.
The least visible item is the one that hurts most in the longer run: the price the brand can command, which depends on the perception of quality built by every previous order.
| Failure item | Direct cost | Hidden cost |
|---|---|---|
| Rework | Operator time | Line disruption |
| Sorting | Inspection time | Delayed dispatch |
| Scrap | Material and labour | Capacity consumed |
| Replacement run | Material and setup | Another order displaced |
| Air freight | Freight premium | Planning credibility |
| Market return | Freight and credit | Customer confidence |
| Repeat failure | Repeat of all above | Account at risk |
| Late delivery | Penalty or discount | Future order size |
The Asymmetry of Cost by Stage
The same defect costs different amounts depending on how far the goods have travelled when it is found. That escalation is the core argument for prevention.
Cost Escalation Through the Process
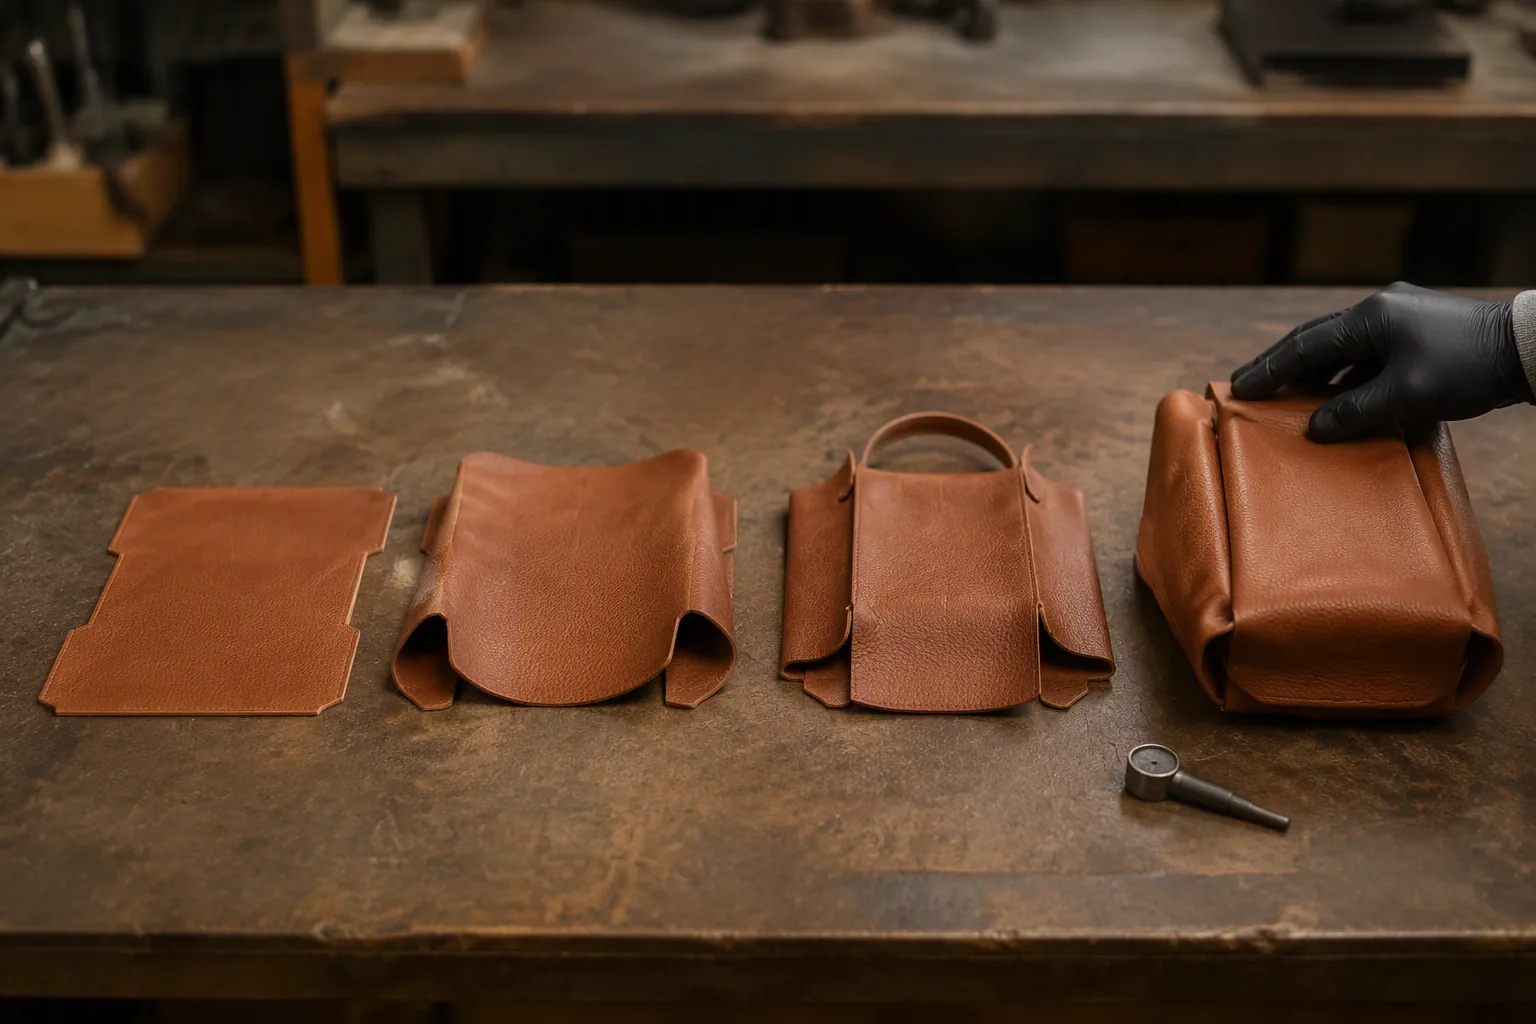
A mis-cut panel found at the cutting table costs one panel. The same panel found after assembly costs the panel, the labour added to it and the material joined to it. Found after packing, it also costs the packing material and the carton.
Found at the customer, it adds freight in both directions, inspection, replacement and the commercial consequence.
Why the Multiplication Matters More Than the Amount
The escalation is multiplicative rather than additive, which is why a defect with a low absolute cost at the bench can be expensive by the time it ships.
A defect that costs one unit of effort at cutting is commonly described in terms of a multiple of that unit further downstream, and the multiple is what should drive where the checks are placed.
Where the Multiplier Is Highest
The highest multipliers sit at the operations that are hardest to undo: assembling panels permanently, closing a lining, attaching hardware through the material and packing the finished bag.
That is why checkpoints belong before those operations rather than after them.
| Found at | Cost includes | Effect on the order |
|---|---|---|
| Cutting | One panel | Local re-cut |
| Preparation | Panel plus preparation time | Re-prepare |
| Assembly | All joined components | Unpick or scrap |
| Hardware fitting | Components plus material | Repair with visible traces |
| Packing | Product plus packaging | Unpack and repack |
| Loading | Product plus handling | Shipment delay |
| Customer | Freight, credit, replacement | Commercial damage |
The Cost of a Missed Checkpoint
Where a checkpoint is missing, the defect it would have caught is found later and costs the escalation multiple. Comparing the two stages is what justifies the extra minute at the bench.
Recording the stage at which each defect was found is enough to make that comparison from ordinary production records.
Measuring Your Own Numbers
A generic argument about the cost of quality convinces nobody. Numbers from your own orders do, and they are simpler to produce than most people expect.
A Workable Minimum
Four quantities per order are enough to make the structure visible: the units inspected, the defects found, the hours spent on rework and sorting, and the units replaced or credited.
Add the stage at which each defect was found, and the escalation becomes visible as well, which is usually the most persuasive part of the picture.
Building the Comparison Over Several Orders
One order gives an anecdote; several orders give a pattern. Where the same defect appears in three consecutive orders, the additional hours it consumed can be totalled and set against the cost of the change that would remove it.
That comparison does not require precision. An order of magnitude is enough to decide between a gauge and another season of sorting.
What to Leave Out
Estimates of reputation damage and future order size are real but not measurable, and including them weakens the case rather than strengthening it. They belong in the discussion, not in the calculation.
Keeping the model to recorded quantities is what makes it credible to a manager who is being asked to release capacity for a change.
| Quantity | Source | What it shows |
|---|---|---|
| Units inspected | Inspection record | Exposure |
| Defects by type | Inspection record | Which defect matters |
| Stage found | Checkpoint record | Escalation cost |
| Rework hours | Production record | Absorbed cost |
| Sorting hours | Inspection record | Absorbed cost |
| Units replaced | Material record | Material and capacity |
| Credits issued | Sales record | External failure |
| Prevention spend | Tooling and engineering | The other side of the comparison |
Why Rework Is Rarely as Cheap as It Looks
Rework is usually billed at operator time, which is the smallest part of what it consumes.
The Schedule Cost
Rework happens inside a schedule that was planned without it. The hours it takes are hours that were committed to the next order, so the cost appears later as a delayed shipment or a compressed final week.
Compressed final weeks are also where secondary defects are made, which links the cost of rework directly to the next round of failure.
The Quality Risk
A reworked unit is not equivalent to a unit made correctly the first time. Unpicked stitching leaves needle holes, replaced panels rarely match the original shade exactly, and hardware refitted through the same holes can be weaker.
Where rework is invisible and durable, it is a sound disposition. Where it is visible or weakens the joint, it transfers the defect to the customer.
The Capacity Cost
Rework consumes the same machines, benches and skilled people as production. Every hour spent on it is an hour not sold, which is a real cost even when no invoice is issued.
Where a line is running at capacity, that cost is the largest of the three and the least recorded.
| Rework cost | How it is recorded | Why it is missed |
|---|---|---|
| Operator hours | Production record | Sometimes not separated |
| Schedule disruption | Rarely recorded | Appears as a delay later |
| Secondary defects | Not attributed | Counted as a new defect |
| Capacity consumed | Not recorded | No invoice is issued |
| Material replaced | Material record | Sometimes written off |
| Shade or hole traces | Not recorded | Invisible in a defect count |
Separating Rework Hours From Production Hours
Production records often absorb rework hours into the same line, which hides both the cost and the capacity it consumed. Separating the two makes the consumption visible without changing the work.
The separation also lets the same hours be compared with the hours the proposed change would save.
Where Prevention Pays Most in Bag Production
Prevention is not evenly valuable across a bag line. A small number of changes carry most of the return, and they are usually the same changes across styles.
The Five Highest-Return Controls
The first is a written tolerance on every dimension that is checked, because it converts inspection from opinion into measurement. The second is a cutting template or go-gauge, because cutting errors propagate through every operation that follows.
The third is approval of the hardware batch at receipt, because hardware faults found after assembly cost material as well as components. The fourth is a first-article approval at the start of each lot, because it catches setup drift before volume is made.
The fifth is a sealed sample held by both parties, because it removes the possibility of a dispute about what was agreed.
Why These Five
Each of the five acts before the cost escalation begins, and each removes a class of defect rather than a single occurrence. They also share a property that makes them easy to approve: they are one-time or low-cost compared with the material and hours they protect.
Where a brand must choose, these are the changes that should be made first.
The Order to Make Them In
Where a line has no written tolerances, that comes first, because gauges and checkpoints need values to check against. Cutting templates follow, then hardware receipt checks, then first-article approval, then the sealed sample routine.
The sequence matters less than starting, because the first two changes usually pay for the rest within a season.
| Control | Applied where | Defect class removed |
|---|---|---|
| Written tolerances | Throughout | Interpretation disputes |
| Cutting template | Preparation | Wrong size and shape |
| Hardware receipt check | Incoming | Faulty components |
| First-article approval | Start of each lot | Setup drift |
| Sealed sample | Throughout | Reference disputes |
| Edge and seam standard | Assembly | Workmanship variation |
| Colour viewing conditions | Assembly and final | Shade disagreement |
Where Prevention Stops Paying
Prevention spend has a limit, and recognising it prevents quality budgets from becoming a source of waste in their own right.
Diminishing Returns
The first changes remove the largest defects. Later changes remove smaller ones at similar cost, and at some point the cost of removing another defect exceeds what the defect costs.
That point differs by defect class: for a critical defect it is far away, and for a cosmetic one it may be reached quickly.
Over-Inspection as a Cost
Inspection is appraisal rather than prevention, and it scales with volume. Where a checkpoint is added to catch a defect that no longer occurs, the cost continues while the benefit does not.
Checkpoints should be reviewed against the defect data and removed when the data shows they are no longer needed.
When Appraisal Is the Right Answer
Some defects are cheaper to find than to prevent: an incoming material fault that varies between deliveries is more economically handled by sampling at receipt than by qualifying every tannery to a zero-defect standard.
The test is the same in both directions: compare the cost of the control with the cost of the defect it prevents, using the recorded quantities rather than an impression.
| Situation | Better answer | Reason |
|---|---|---|
| Defect with high downstream cost | Prevention | Escalation dominates |
| Defect that no longer occurs | Remove the checkpoint | Cost continues, benefit does not |
| Variable incoming material | Appraisal at receipt | Cheaper than qualifying every source |
| Cosmetic defect at high removal cost | Accept within limits | Removal costs more than the defect |
| Critical or safety defect | Prevention at any reasonable cost | Consequence not comparable |
| Rare defect with cheap detection | Appraisal | Detection is the lower cost |
Making the Case Internally
A quality improvement that depends on a conviction rather than a calculation rarely survives the first busy month. The case has to be presented in the language the decision maker already uses.
Converting Defects Into Hours and Units
The most effective presentation states the defect in units and hours: how many units were affected, how many hours were consumed sorting and reworking them, and how many units were replaced.
Hours and units are quantities that a production manager already plans with, and they avoid the argument about estimates.
Setting Spend Against Consumption
The change is then set against the same units: the cost of the gauge, template or changeover expressed in the same terms as the consumption it removes. Where the change pays back within one or two orders, the decision is straightforward.
Where it does not, the case is weaker and should be presented as one, rather than supported with estimates that cannot be defended.
Presenting It as a Choice Rather Than a Complaint
A quality proposal framed as a complaint about workmanship invites a defence. The same proposal framed as a choice between two ways of spending the same hours invites a decision.
The framing matters because the person approving the change is usually the person who would also have to absorb the rework.
| Presentation | Effect | Alternative |
|---|---|---|
| Defect counts alone | Feels like an inspection report | Add stage and hours |
| Hours consumed | Decision maker's own language | Keep to recorded values |
| Units replaced | Material and capacity | Include the displaced order |
| Spend versus consumption | Direct comparison | Use the same units |
| Complaint about workmanship | Invites defence | Frame as a choice |
| Estimates of lost reputation | Discounted and forgotten | Keep in discussion, not the sheet |
Who Should Carry the Cost
Quality cost is shared between the brand and the factory, and where the split is unclear the cost is usually carried by whoever notices it last.
Cost Inside the Factory
Where a defect originates in the factory process, the correction, sorting, rework and replacement belong to the factory. Writing that into the order converts each incident from an argument into a calculation.
The factory's own prevention spend is the part it controls, and it is usually the part that pays back fastest for them, because the hours recovered are hours it can sell.
Cost Inside the Brand's Decisions
Where a defect originates in the brand's specification, artwork or late change, the cost belongs to the brand. That includes unclear tolerances, unstated requirements and changes made after material was ordered.
Recognising this boundary is what makes the process credible, because a supplier who is charged for the buyer's ambiguity will stop reporting problems early.
Cost at the Boundary
Some costs sit between the two: material that meets the stated specification but fails in use, hardware that passes receipt and fails after assembly, or a design that is difficult to make consistently.
These are the cases worth resolving once with a written decision, because they recur and each recurrence consumes goodwill as well as money.
| Origin of defect | Who carries the cost | Written where |
|---|---|---|
| Factory process | Factory | Order terms |
| Factory material handling | Factory | Order terms |
| Unclear specification | Brand | Order terms |
| Late change by brand | Brand | Change control |
| Material meeting spec, failing in use | Shared, by agreement | Specification review |
| Design difficult to make | Shared, by agreement | Pre-production review |
| Transit damage | Per delivery terms | Shipping terms |
Tracking It Over Time
A single improvement is invisible in a season's data. Tracking is what turns individual decisions into a direction.
Setting a Baseline
The baseline should be recorded before the changes: defects by type, stage found, hours consumed and units replaced across a defined period, expressed per order or per hundred units so that volume does not distort the comparison.
Without a baseline, improvement is a matter of opinion, and opinions revert under pressure.
Reviewing on a Fixed Cadence
A short review after each order keeps the numbers current, and a longer review each season compares the categories: prevention spend, appraisal spend, internal failure and external failure.
Where prevention spend rises and internal failure falls by more, the direction is right, even if total spend looks higher in the short term.
When the Numbers Move the Wrong Way
A rise in internal failure with unchanged prevention spend usually indicates that the operation has changed rather than that reporting has improved: a new material, a new operator on a sensitive operation or a busy period that compressed the checks.
The useful response is to look at the stage where the increase appeared rather than to add a checkpoint at the end.
| Tracking element | Frequency | Purpose |
|---|---|---|
| Defects by type | Per order | Which defect costs most |
| Stage found | Per order | Where the escalation occurs |
| Rework and sorting hours | Per order | Absorbed cost |
| Units replaced | Per order | Material and capacity |
| Prevention spend | Per season | The other side of the ledger |
| Appraisal spend | Per season | Whether checks still earn their place |
| External failure | Per season | Whether defects reach the market |
Agreeing a Review Date
A tracking routine survives on a date rather than on good intentions. Fixing the next review when the current one closes keeps the comparison moving even through a busy season.
Where the date is missed, the useful response is to review the following order rather than to abandon the routine.
FAQ
Why is prevention usually cheaper than rework?
A: Because the cost of a defect multiplies as the goods move through production. A fault found at cutting costs one panel, while the same fault found after assembly costs the panel plus everything joined to it.
What are the four categories of quality cost?
A: Prevention (stopping defects being made), appraisal (finding them), internal failure (catching them before shipment) and external failure (finding them after shipment).
Why is quality cost often measured incorrectly?
A: Because only the invoiced items are counted. Rework labour and sorting appear on the ledger, while lost capacity, delayed shipments and engineering time spent chasing a defect appear elsewhere or nowhere.
What does prevention actually include?
A: Written specifications and tolerances, gauges and templates, sealed samples, supplier qualification, tooling maintenance, and training against a written standard.
Is inspection prevention?
A: No. Inspection is appraisal: it finds defects rather than preventing them, and its cost scales with volume. It reduces what reaches the customer, not how many defects are created.
Why does rework cost more than the hours suggest?
A: Because it consumes scheduled hours, displaces the next order, risks secondary defects in a compressed final week, and occupies capacity that could have been sold.
How can a brand measure its own quality cost?
A: Record four quantities per order: units inspected, defects by type, hours spent on rework and sorting, and units replaced or credited. Adding the stage at which each defect was found shows the escalation.
Where does prevention pay most in bag production?
A: Written tolerances, a cutting template or go-gauge, hardware checks at receipt, first-article approval at the start of each lot, and a sealed sample held by both parties.
Can prevention spending be wasted?
A: Yes, at the point of diminishing returns, and through checkpoints left in place after the defect they were added for has stopped occurring. Controls should be reviewed against current defect data.
When is inspection a better answer than prevention?
A: Where a defect is cheaper to detect than to prevent, such as incoming material that varies between deliveries and would otherwise require qualifying every source to the same standard.
Who should pay for rework?
A: The party whose decision created the defect: the factory for process and handling causes, the brand for unclear specifications and late changes, and a written agreement for cases that sit between them.
Why should the cost split be written into the order?
A: Because where the split is unclear, the cost is carried by whoever notices it last, and the party that absorbs another party's ambiguity stops reporting problems early.
What is a useful baseline for quality cost?
A: Defects by type, stage found, hours consumed and units replaced over a defined period, expressed per order or per hundred units so that volume does not distort the comparison.
How often should the numbers be reviewed?
A: A short review after each order keeps the data current, with a season-level review comparing prevention, appraisal, internal failure and external failure.
What does a rise in internal failure with unchanged prevention spending mean?
A: Usually that something in the operation changed, such as a new material, a new operator on a sensitive step, or a busy period that compressed the checks. Look at the stage where the increase appeared.
Does a higher total quality spend always mean a worse result?
A: No. Where prevention spend rises and internal failure falls by more, the direction is right even if the total looks higher in the short term.
Ready to argue for prevention with numbers rather than instinct? Record defects, stages and hours on the next three orders, total what one defect class actually consumed, set it against the cost of the change that would remove it, start with written tolerances and a cutting template, review the checkpoints that no longer earn their place, and let the recorded quantities rather than the impression decide where the next quality spend goes.